
Magalu Jumps 11% on B3 Following Q3 Profit and Bank of America Buy Rating
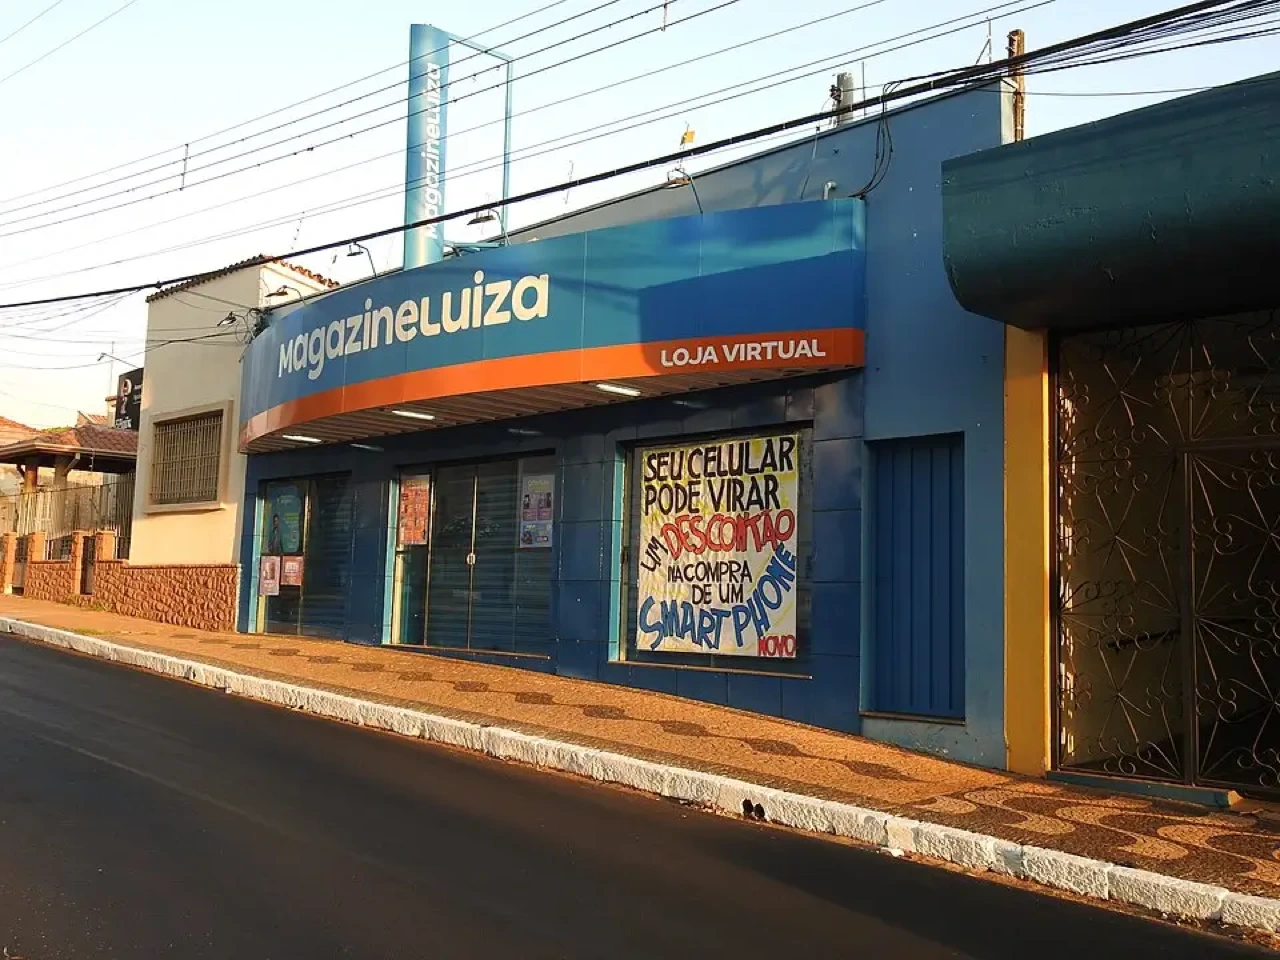
The Brazilian retail powerhouse returns to profitability in the third quarter, posts double-digit sales growth in October, and receives an upgraded target price of R$ 11.
SÃO PAULO — Shares of Brazilian retail giant Magazine Luiza gained 11.2% on the B3 stock exchange this week. The rally followed third-quarter financial results that exceeded market consensus and an investment rating upgrade by Bank of America.
The financial institution upgraded Magazine Luiza from Underperform to Buy. Bank of America lead analyst Robert Aguilar set a price target of R$ 11 per share. The projection implies an upside potential of 70% from current trading levels.
Operational Turnaround and Profitability in Q3
The retail chain posted an adjusted net profit of R$ 70.2 million for the third quarter of 2024. The performance marks a complete turnaround from the adjusted net loss of R$ 143.4 million reported in the same quarter of 2023.
Net revenue reached R$ 9.0 billion during the period, representing a 4.9% increase year over year. Adjusted EBITDA reached R$ 717.6 million, up 47.2% compared to R$ 487.5 million in the prior-year period.
Adjusted EBITDA margin expanded to 8.0%, an increase of 2.3 percentage points. Magazine Luiza Chief Executive Officer Frederico Trajano stated during an earnings conference call that management prioritized operational discipline, gross margin defense, and free cash flow generation.
Sales Acceleration in Physical Stores and E-Commerce
Bank of America highlighted an operational inflection point in preliminary fourth-quarter data. Same-store sales in physical locations climbed 16% in October, while proprietary digital commerce revenue expanded 14%.
The research note emphasized market share gains captured from direct competitors. Chief domestic rival Casas Bahia continues executing a court-approved out-of-court restructuring plan covering R$ 4.1 billion in debt. In response to requests for comment, Casas Bahia stated that its strategic focus remains on store profitability and network rationalization.
Deleveraging also reinforced the rating upgrade. Magazine Luiza reduced its net debt to adjusted EBITDA ratio to 1.3 times in September, down from 2.6 times twelve months earlier.
Source: Brazilian Securities and Exchange Commission (CVM), Magazine Luiza S.A., and Bank of America Global Research
Related Stories
GTA 6 Tests Console Hardware Limits and Pressures PC Release Window
Take-Two Interactive locks in a November 2026 launch date as generative reverse engineering and unified memory constraints rewrite industry playbooks.
Ring Flying Drone Challenges Privacy and Limits of Edge Computing
Amazon's shift from static IoT cameras to indoor spatial robotics introduces real-time on-device SLAM alongside serious domestic mapping liabilities.